How you can pay for a roof in Cape Coral
Where insurance comes in, how financing works and what a state program might chip in, all done by Florida's roofing laws as written.
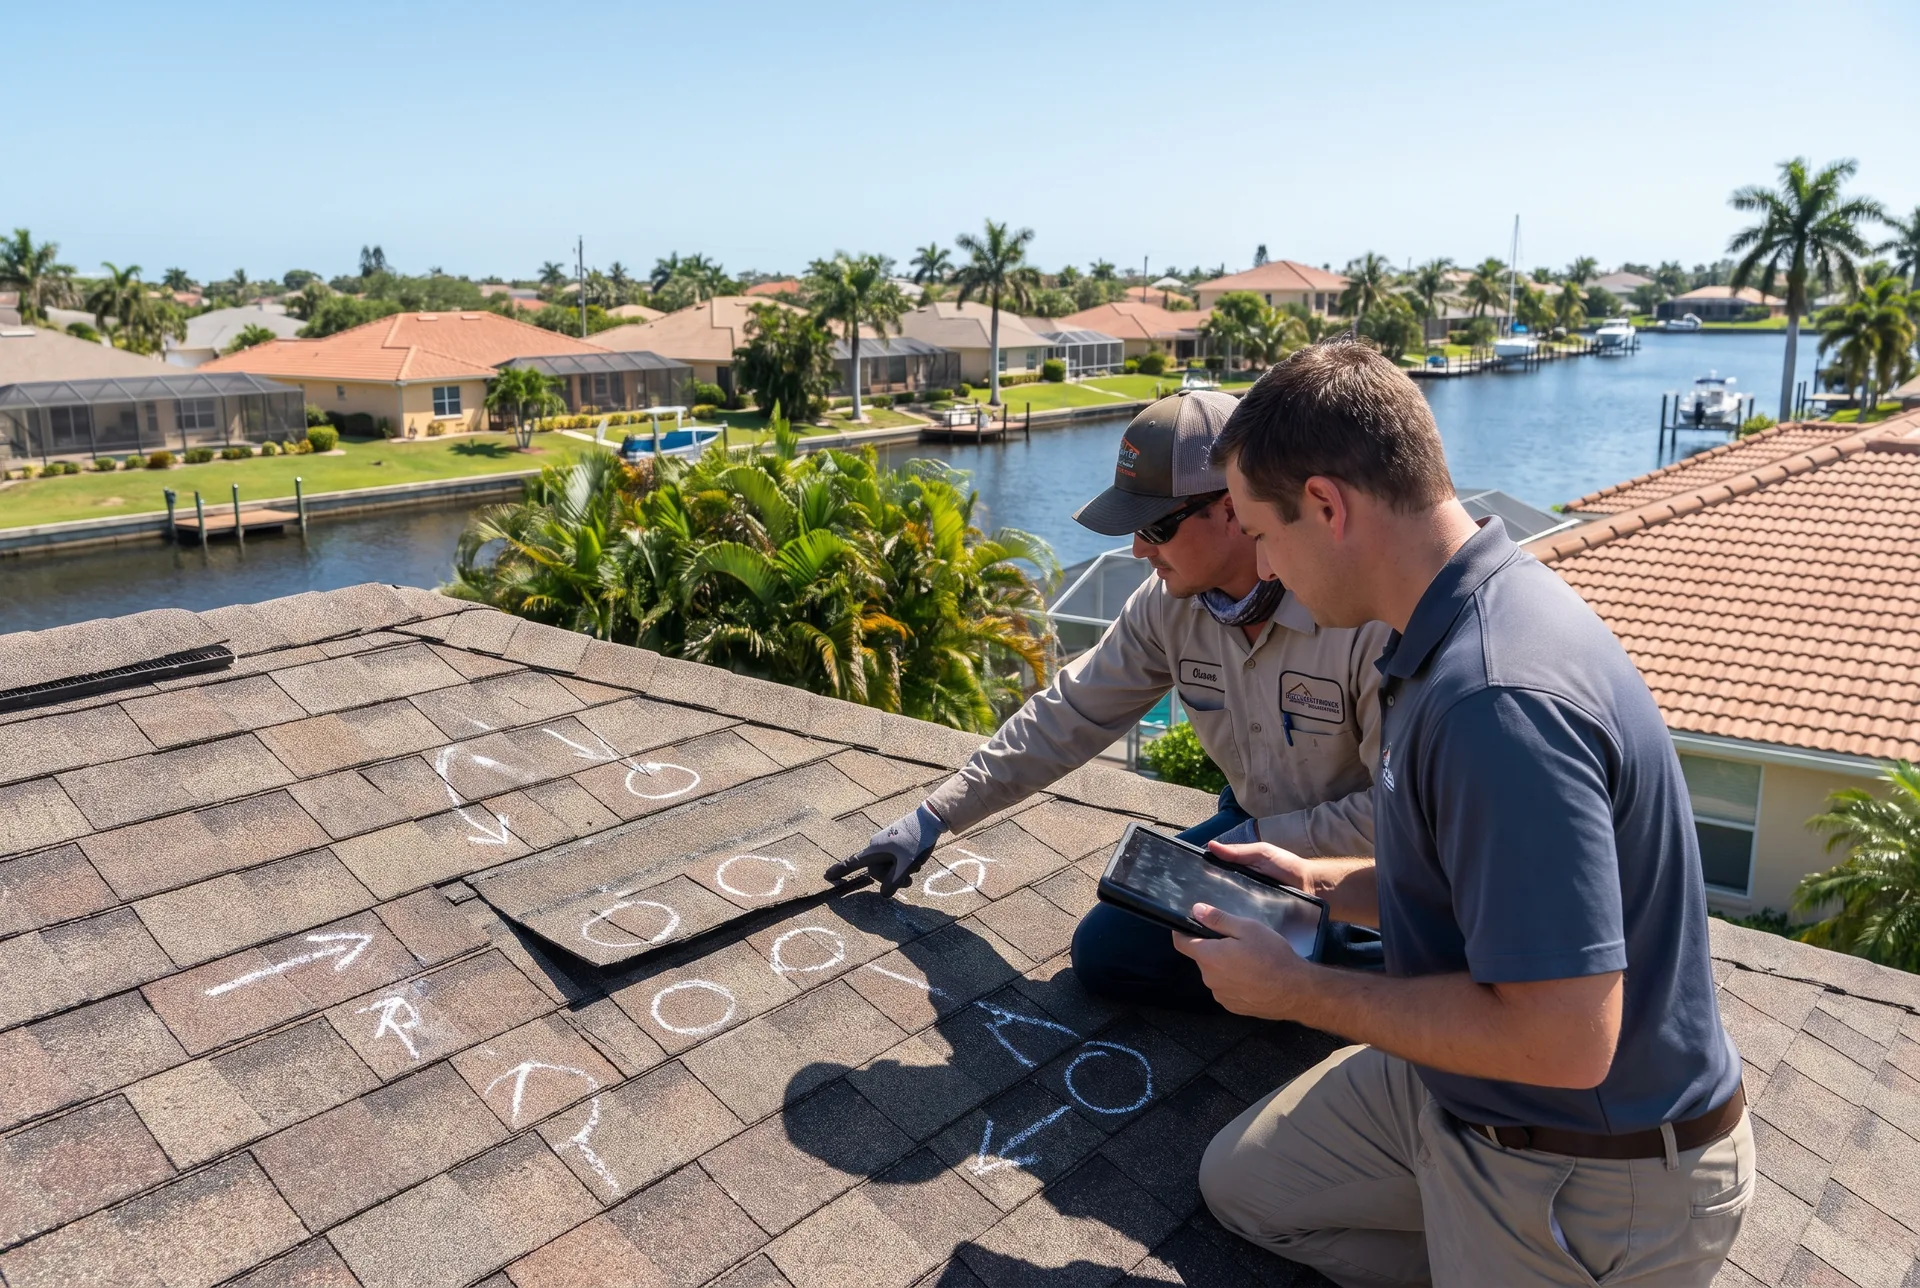
The money side, from signing to the final inspection
You'll get a written, itemized price that stays good for 30 days. When you sign, a deposit lets us order your materials; it's bigger on tile and metal, since those are ordered to fit your roof. The rest is due once the work's done and the final inspection passes. Pay by card, check, ACH or financing. You'll never hand money to a crew on your roof.
Spreading out the cost
Most roofs around here get financed, at least in part. Our lending partners offer 12-month same-as-cash promotions and fixed-rate terms as long as 10 years. You're approved before we start, with no penalty for paying early, which helps when an insurance check or a My Safe Florida Home reimbursement is still on its way. Applying takes a few minutes on a soft credit pull, and we never see your credit details.
Three times your insurance comes into it
After a storm
We photograph the damage and write it down. Filing is your call; if you do, we'll meet your adjuster and build what the approved scope covers. Here's how a claim works with us.
When your insurer asks how old the roof is
We'll inspect it free. If the roof truly has life left, you get the remaining-life letter under F.S. 627.7011; if not, an honest talk about repair, re-underlayment or replacement. Our roof age guide has the rules.
Wind mitigation
The OIR-B1-1802 report turns the code features in your roof into premium credits. It's free whenever we replace your roof.
Things you won't catch us doing
We won't solicit a claim, pay or waive your deductible, hand out gifts for filing, or take an assignment of benefits. Florida law (F.S. 489.147) bans all of it, and it's a big part of how the last claims crisis got going.
A boost from the state
If your home was built before 2008, is homesteaded and is insured for under $700,000, My Safe Florida Home matches 2-to-1, up to $10,000, on wind-mitigation upgrades, the code parts of a re-roof included. Here's how you can use it.